How Much Does a Fiduciary Financial Advisor Cost in 2026?
Delve into the realm of fiduciary financial advisor costs in 2026, where intricate factors and evolving fee structures shape the landscape of financial advisory services. Unravel the mysteries behind pricing and regional variances, while exploring the impact of technology on costs.
Join us on this journey to uncover the future expenses of fiduciary financial advisors.
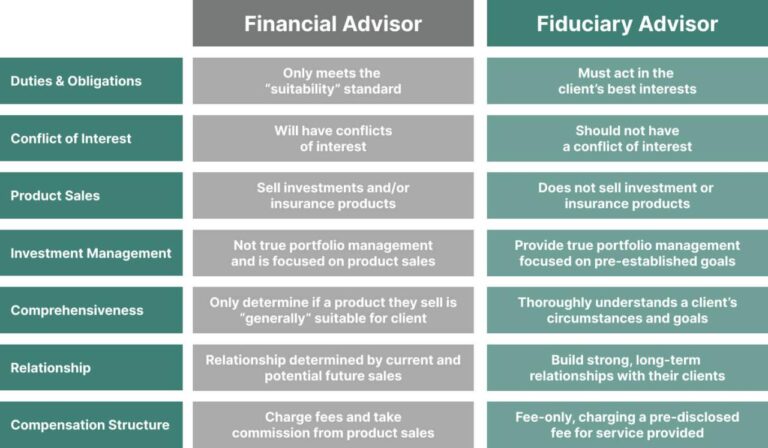
When considering the cost of hiring a fiduciary financial advisor, several key factors come into play that can impact the overall pricing. These factors can range from economic conditions and market trends to the complexity of an individual’s financial situation.
Understanding these elements is crucial in determining how much you might expect to pay for fiduciary services.
The state of the economy and prevailing market trends play a significant role in determining the cost of hiring a fiduciary financial advisor. During times of economic uncertainty or market volatility, advisors may adjust their fees to reflect the increased risk and potential challenges in managing investments.
Similarly, when the economy is thriving and markets are performing well, advisory fees may be higher due to increased demand for services.
Changes in regulatory requirements can also impact the cost of fiduciary financial advisor services. As regulations evolve and become more stringent, advisors may need to invest additional time and resources to ensure compliance, which can lead to higher fees for clients.
Staying abreast of regulatory changes and adapting to new requirements can increase the overall cost of hiring a fiduciary advisor.
The complexity of an individual’s financial situation can significantly influence advisory fees. Clients with intricate investment portfolios, multiple income sources, estate planning needs, or tax considerations may require more specialized expertise and time from a fiduciary financial advisor. As a result, the cost of services is likely to be higher for clients with more complex financial situations compared to those with simpler needs.
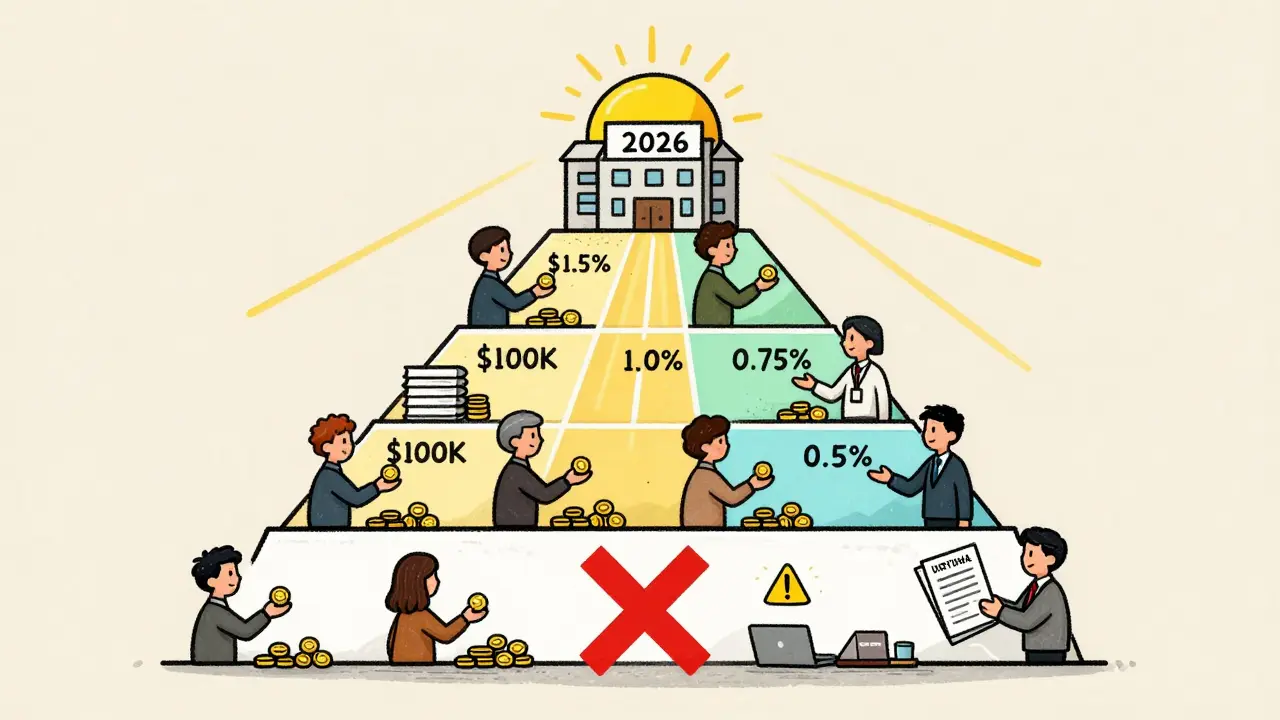
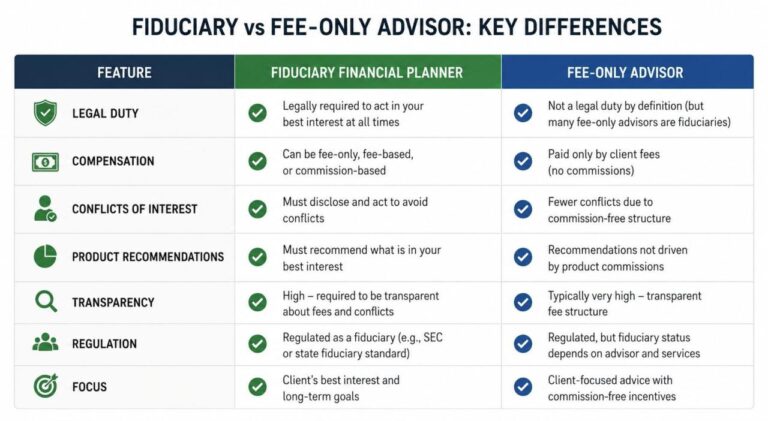
When it comes to fiduciary financial advisors, fee structures play a crucial role in determining how clients will be charged for the services provided. Let’s explore the different fee structures commonly used in fiduciary financial advisory services and their respective advantages and disadvantages for clients.
Hourly rates are a fee structure where clients pay for the time spent by the financial advisor on their financial planning needs. This can be beneficial for clients who require occasional advice or have specific one-time financial questions.
Flat fees involve clients paying a set amount for a specific range of financial planning services, regardless of the time spent by the advisor. This fee structure provides predictability for clients in terms of costs.
Asset-based fees are calculated as a percentage of the client’s assets under management by the financial advisor. This fee structure aligns the advisor’s interests with the client’s financial growth.
As the financial advisory industry continues to evolve, we may see a shift towards more hybrid fee structures that combine aspects of different models to provide tailored solutions for clients. Additionally, advancements in technology may lead to more transparent pricing models and fee structures that better reflect the value provided by fiduciary financial advisors.
When it comes to fiduciary financial advisor costs, geographic location plays a significant role in determining the final price tag for these services. Different regions may have varying costs due to a variety of factors.
One of the main drivers of regional variances in fiduciary financial advisor costs is the distinction between urban and rural areas. In general, financial advisors in urban centers tend to charge higher fees compared to their counterparts in rural areas.
This is often attributed to the higher cost of living and operating a business in cities.
Aside from urban-rural divides, regional regulations and practices can also impact fiduciary financial advisor costs. Different jurisdictions may have varying licensing requirements, compliance standards, and professional practices that influence pricing.
For example, some regions may have stricter regulations that necessitate more extensive training or certification for financial advisors, leading to higher costs for their services.
The advancement of technology has significantly influenced the landscape of financial advisory services, including the costs associated with hiring fiduciary financial advisors. Technological tools such as AI, automation, and online platforms have reshaped how financial advice is delivered and received, ultimately impacting the pricing structure of these services.
Robo-advisors have emerged as a popular and cost-effective alternative to traditional fiduciary advisors. These automated platforms utilize algorithms and data analysis to provide investment advice and portfolio management at a fraction of the cost of human advisors. By leveraging technology, robo-advisors offer streamlined services that cater to clients looking for a more affordable option without compromising on the quality of financial advice.
As technology continues to evolve, the cost landscape for fiduciary financial advisors is expected to undergo further transformation by 2026. The integration of AI and machine learning algorithms may enhance the efficiency of human advisors, enabling them to deliver personalized financial advice at a lower cost.
Additionally, the rise of digital platforms and online investment tools could lead to increased competition among financial service providers, driving prices down as firms strive to attract and retain clients in a digital-first environment.
It is anticipated that technological innovations will drive down the overall cost of financial advisory services, making professional guidance more accessible to a broader range of investors.
How do economic conditions affect fiduciary financial advisor costs?
Economic conditions can impact costs by influencing demand for services and affecting investment opportunities, which in turn may alter fee structures.
What are the advantages of asset-based fees for clients?
Asset-based fees align the advisor’s interests with the client’s investment performance, potentially fostering a more collaborative relationship.
How do costs vary between urban and rural areas for fiduciary financial advisory services?
Urban areas tend to have higher costs due to higher living expenses and greater demand, while rural areas may offer more competitive pricing.
What role do robo-advisors play in lowering costs for clients?
Robo-advisors leverage technology to provide automated, cost-effective investment solutions, offering clients a more affordable alternative to traditional advisors.