Best Business Line of Credit Options for Working Capital and Cash Flow
Delving into Best Business Line of Credit Options for Working Capital and Cash Flow, this introduction immerses readers in a unique and compelling narrative, with a casual formal language style that is both engaging and thought-provoking from the very first sentence.
Exploring the different types of business lines of credit, their benefits, and how they can be a valuable tool for managing working capital and cash flow needs is crucial for any business looking to optimize its financial resources. In this overview, we will delve into the intricacies of business lines of credit and provide insights into their relevance in today’s dynamic business environment.
A business line of credit is a flexible form of financing that allows businesses to access a predetermined amount of funds, similar to a credit card. However, unlike traditional loans with a fixed amount, a business line of credit gives business owners the ability to borrow funds as needed, up to a certain limit.
When it comes to working capital and cash flow needs, a business line of credit can be a valuable tool. It provides quick access to funds to cover operational expenses, manage seasonal fluctuations, seize growth opportunities, or bridge gaps in cash flow without the need to apply for a new loan each time.
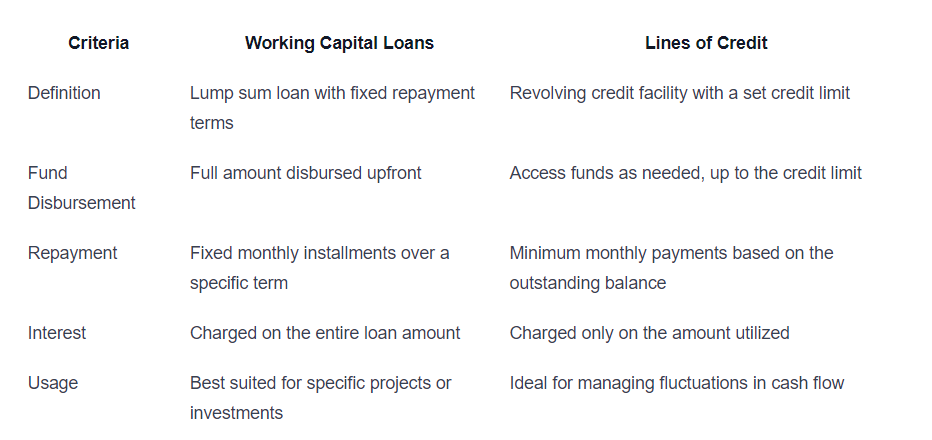
When it comes to business lines of credit, there are different types available in the market to suit various business needs. Let’s compare and contrast these types, detailing the eligibility criteria, typical interest rates, repayment terms, and credit limits associated with each.
A secured business line of credit requires collateral, such as inventory, equipment, or real estate, to secure the credit line. Eligibility criteria often include a strong credit score, stable revenue, and valuable assets. Interest rates are usually lower compared to unsecured options, and credit limits are determined based on the value of the collateral provided.
An unsecured business line of credit does not require collateral but typically demands a higher credit score and revenue stability. Interest rates are usually higher than secured options due to the increased risk for the lender. Credit limits are determined based on the business’s financial health and creditworthiness.
A revolving business line of credit allows businesses to borrow funds up to a predetermined credit limit, repay, and borrow again without needing to reapply. This type offers flexibility in managing cash flow and working capital. Interest rates can vary based on the lender and creditworthiness of the business.
Seasonal business lines of credit are designed to help businesses manage fluctuations in cash flow during peak seasons. Eligibility may depend on demonstrating a history of seasonal revenue patterns and the ability to repay the credit during off-peak periods. Interest rates and credit limits can be adjusted based on the seasonal nature of the business.
Short-term business lines of credit provide quick access to funds for immediate business needs, such as covering payroll or unexpected expenses. Eligibility criteria may include a minimum time in business and revenue requirements. Interest rates are typically higher, but repayment terms are shorter, offering a quick solution for temporary cash flow gaps.
When it comes to finding the best business line of credit options for working capital and cash flow, there are several top choices available. Each option comes with its own set of features, benefits, and drawbacks, so it’s important to understand the details before making a decision.
A traditional bank line of credit is a common option for businesses looking for financing. It typically offers competitive interest rates and flexible repayment terms. However, the application process can be lengthy, requiring extensive documentation and a good credit score.
Business credit cards are another popular choice for accessing a line of credit. They offer convenience and flexibility, with the ability to earn rewards on purchases. However, interest rates can be high, and overspending can lead to debt accumulation.
Online lenders provide a quick and easy way to access a business line of credit. They often have lenient requirements and fast approval processes. However, interest rates may be higher compared to traditional banks, and the terms may not be as favorable.
Invoice financing allows businesses to borrow against their outstanding invoices. This can provide quick access to cash flow without taking on additional debt. However, the fees associated with invoice financing can be costly, impacting the overall profitability of the business.
Asset-based lending uses business assets, such as inventory or equipment, as collateral for a line of credit. This can be a viable option for businesses with valuable assets but may carry the risk of losing those assets if the loan is not repaid.
The interest rates can also be higher than other options.
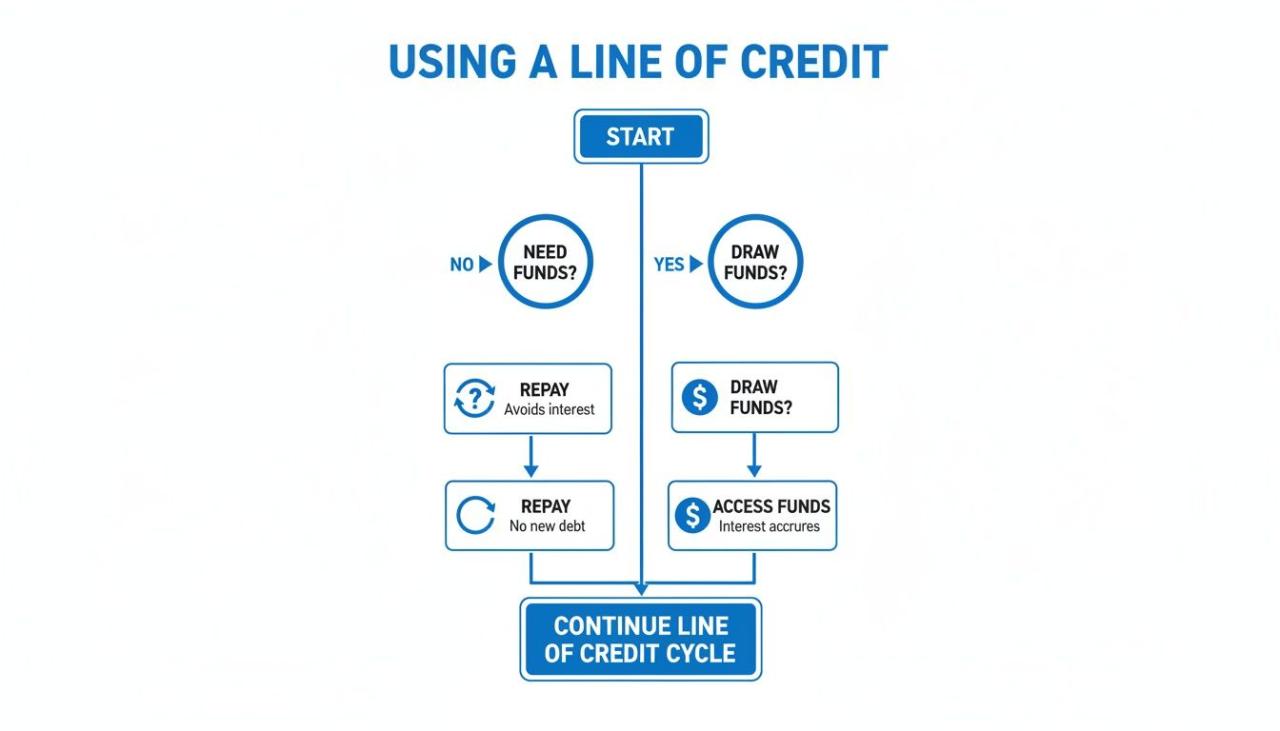
When it comes to selecting a business line of credit for working capital and cash flow, there are several important factors to consider. Evaluating different options carefully and comparing terms, fees, and flexibility is crucial in making the right decision for your business needs.
Comparing the terms, fees, and flexibility of different business lines of credit is essential in ensuring that you choose the right option for your business. By evaluating these factors, you can select a line of credit that suits your financial needs and helps you maintain a healthy cash flow.
What are the usual eligibility criteria for a business line of credit?
Eligibility criteria typically include a minimum credit score, business revenue, and time in operation.
How do interest rates for business lines of credit usually compare to traditional loans?
Interest rates for business lines of credit are often lower than traditional loan rates due to the revolving nature of the credit line.
What documentation is usually required when applying for a business line of credit?
Commonly required documents include financial statements, tax returns, and business plans.